Daily newsletter · Sat 7 Nov 2026
Cloudflare grew revenue 39%, its fastest in nearly four years
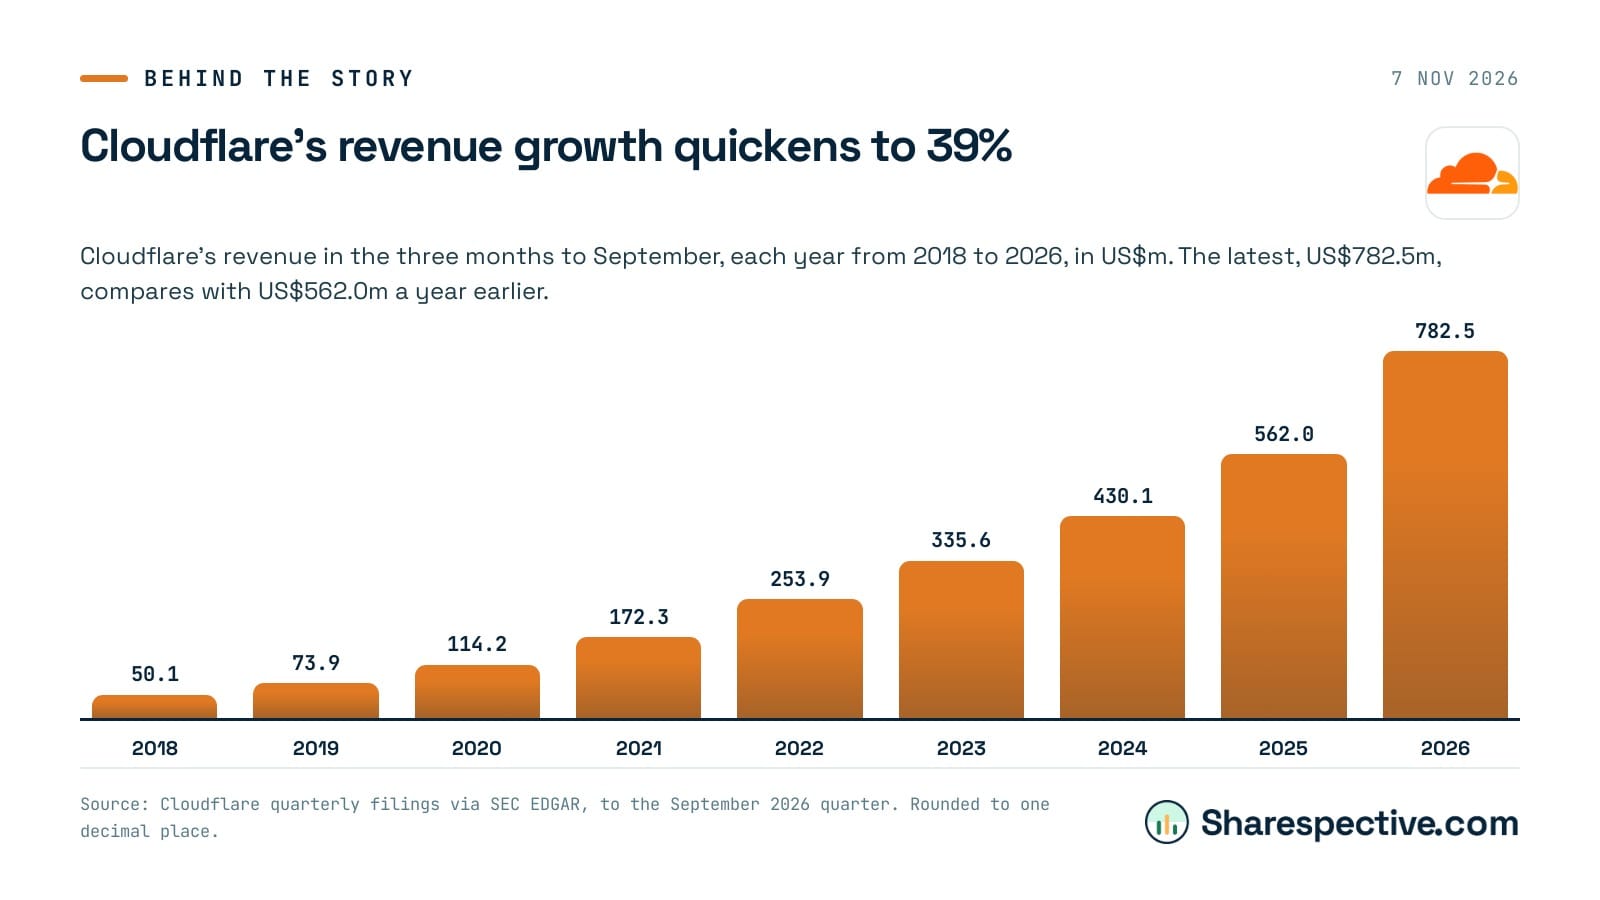
Cloudflare reported revenue of US$782.5 million for the September quarter, up 39% on a year earlier. Analysts had expected about US$736.8 million. The shares rose 9.91% to US$268.75 on Friday.
That is the fastest Cloudflare has grown in nearly four years. Adjusted earnings came in at 38 US cents a share against the 34 cents expected. Billings, which count what customers have agreed to pay, rose 35.5% to US$846.2 million.
The forecast did more than the quarter. Cloudflare guided December-quarter revenue to about US$845.5 million, against the US$795.9 million analysts had pencilled in. Full-year adjusted earnings guidance went to US$1.35 a share, the third raise this year.
Cash improved with it. Free cash flow reached 10.5% of revenue, up from 8.1% a year earlier, and annualised revenue passed US$3 billion. The company still records an operating loss once share-based pay is counted in full.
Cloudflare sells the delivery and security layer that sits in front of AI services, so its growth is bolted to the same buildout the market spent Thursday repricing. One good quarter says nothing about what happens if data centre orders slow.
General information and commentary only, not financial advice. It does not take account of your objectives, financial situation or needs, and reflects the author's own reading of public information at the time of writing, which may be wrong. Sharespective, its people and its clients may hold positions in the companies covered. Do your own research and talk to a licensed adviser.